Global capital markets responded to the midterm elections with a burst of optimism, followed by a brief but revealing period of volatility. Stocks and bonds rallied as investors anticipated that political gridlock could restore institutional balance and impose greater fiscal discipline. Yet enthusiasm faded as attention shifted toward potential regulatory risks and their implications for economic growth. The subsequent sell-off was short-lived, with bargain hunters returning to support equity prices. These rapid shifts offered a useful illustration of how financial markets absorb new information and reassess expectations.
Markets entered the election under considerable macroeconomic strain. Affordability was likely a central concern for voters, particularly as elevated energy costs and mortgage rates continued to pressure household budgets. Government bond yields had climbed to levels not seen in roughly a quarter century, pushing borrowing costs higher, slowing home sales, and weighing on mortgage applications. Meanwhile, conflict in the Middle East added uncertainty to energy markets, effectively imposing an indirect tax on global growth. Equities were also vulnerable as investors increasingly questioned whether substantial technology spending would ultimately deliver attractive returns.
Against this backdrop, the election results surprised investors and initially inspired a favorable market response. The prospect of a divided government suggested fewer opportunities for major policy changes, including legislation that could widen fiscal deficits or alter tax and tariff policies. Both stocks and bonds advanced as markets priced in the possibility of greater policy restraint. Energy prices also declined amid hopes that negotiations in Qatar might ease regional tensions, reinforcing the broader improvement in sentiment.
That optimism proved temporary. By the second day after the election, investors had begun considering the regulatory implications of greater Democratic influence in Congress. Selling spread through technology shares and weighed on global equities. However, buyers returned before the week ended, helping fuel a technology-led rebound.
The volatility after the election was less a sign of market dysfunction than a reflection of price discovery at work. Investors first rewarded the prospect of policy stability, then accounted for emerging risks, and finally reassessed valuations as selling pressure subsided. The speed of that adjustment offered a constructive reminder that markets can process uncertainty without allowing it to define the longer-term outlook.
Midterm Elections
The midterm elections resulted in a significant shift in political power, with Democrats gaining control of both the House and Senate. The outcome creates a divided political environment and represents a challenge to the administration's economic agenda. The election comes at a difficult time for the economy, with elevated interest rates, high energy prices, and escalating geopolitical conflicts adding uncertainty to the broader economic outlook.
Financial market reactions have been both up and down; ultimately, the markets have experienced a significant increase in volatility in both directions.
The election results could have meaningful implications for several industries, particularly technology, energy, healthcare, and housing. Democrats are expected to challenge certain administration policies, including tariffs and energy initiatives, while potentially slowing the expansion of AI-related data center projects. However, divided government could limit the ability to implement significant legislative changes, making executive actions and bipartisan cooperation particularly important.
The broader economic and market implications will hinge on how the political shift affects policy. Investors should prepare for continued volatility as markets assess these political impacts on fiscal policy, trade, energy, and corporate investment.
Inflation & Jobs
The labor market showed mixed signals over the past several weeks. September hiring initially appeared weak before stronger jobless claims and October employment data suggested conditions are more resilient than expected. The economy added 165,000 jobs in October, well above expectations, while the unemployment rate edged down to 4.1%.
The labor market increasingly resembles a low-hire, low-fire environment rather than one experiencing significant weakness. Yet, this poses some challenges for certain segments of the labor markets. Recent graduates and long-term unemployed workers continue to face challenges finding employment, while the median duration of unemployment has risen to its highest level in roughly four and a half years.
Inflation remains a more persistent concern for the Fed. Continued consumer spending and strong household balance sheets are helping support economic activity but are also contributing to persistent price pressures. Inflation has remained near 3% for several years, suggesting that progress toward the Fed's target has stalled.
“The economy added 165,000 jobs in October, well above expectations, while the unemployment rate edged down to 4.1%.”
Another consideration is the household wealth expansion has been uneven by consumer segment, with higher-income households capturing the majority of the increase in wealth. This creates some vulnerability if financial markets weaken, particularly given the significant exposure of wealthier households to equity markets.
The key question is whether tighter financial conditions will eventually slow consumer spending and weaken employment, allowing inflation to decline without creating a more significant economic slowdown.
Federal Reserve
The Federal Reserve held its benchmark interest rate steady at the 3.75% to 4% range at its October meeting. As a reminder, the Fed raised rates by a quarter point in the prior meeting, the first increase since 2023. While the decision was widely expected, two members favored another rate increase. The Fed also upgraded its assessment of economic activity from "solid" to "expanding at a strong pace," while acknowledging that inflation remains elevated.
The decision reinforces the Fed's focus on bringing inflation back to its 2% target despite continued economic resilience. Strong consumer demand, higher wages, and continued economic growth make it more difficult to bring inflation under control. At the same time, tighter financial conditions are beginning to have an effect, although the Fed has not yet determined whether current policy is sufficiently restrictive.
“The decision reinforces the Fed’s focus on bringing inflation back to its 2% target despite continued economic resilience."
The October employment report added to the case for maintaining a restrictive monetary policy. Although some economists view the report as evidence of a strengthening labor market, others believe it reflects stability rather than renewed economic acceleration. Regardless, stronger employment could make it more difficult for the Fed to bring inflation down without additional rate increases.
Stocks
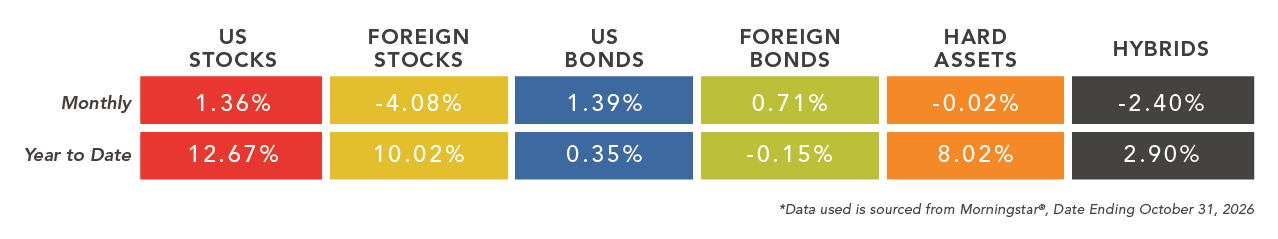
The stock market has experienced massive volatility over the last month, with the likely catalyst being the midterm elections. With the Democratic Party winning control of both chambers of Congress, there seemed to be an immediate concern over potential tightening of AI-industry regulations, stricter anti-trust policies, and a projected slowdown in data center spending.
This sell-off was heavily amplified by financial structuring rather than purely fundamental failures. Many hedge funds and institutional traders used margin to maximize their bets on the AI boom. When the political news triggered initial price drops, these funds faced massive margin calls, forcing them to rapidly liquidate positions at a near-record pace to raise cash, creating a domino effect.
Then, a company-specific risk from Nvidia added another major blow. Nvidia recently issued an official statement confirming an independent board investigation into its CEO. Although this was related to personal matters, it has potential national security implications and a severe "policy overhang," as investors fear it will prompt aggressive congressional inquiries and further restrict international semiconductor trade.
Despite the stock market sell-off, foundational tech companies reported strong numbers. And, although the markets have experienced heightened volatility, they have also experienced attractive rebounds over certain daily market sessions. Beyond that, some market segments have been highly resilient through this recent volatility. This all supports the principles of maintaining a long-term perspective, investment discipline, and proper diversification.
Bonds
The bond market continues to experience one of its longest downturns in US history, as rising interest rates and persistent inflation have pushed Treasury yields to levels not seen in more than two decades. The 10-year Treasury yield reached 5.31% in October, while yields across maturities of seven to 30 years moved above 5%. Investors are demanding greater compensation for holding longer-term bonds, reflecting concerns about inflation, government borrowing, and the sustainability of federal debt.
The impact of higher interest rates has been particularly significant for longer-duration bonds. Over the past five years, long-term Treasuries have experienced substantial losses, while shorter-term maturities have held up considerably better.
Increased yields increase borrowing costs for consumers, businesses, and the federal government. Yet, these higher yields are also creating more attractive opportunities for new fixed-income investors. The current interest rate environment can now provide investors with an opportunity to earn a return above inflation while also creating greater competition for stocks.
© Advisory Alpha. Registration with the SEC or a state does not constitute an endorsement of the firm by regulators, nor does it indicate that the adviser has attained a particular level of skill or ability. This content is for informational purposes only and does not intend to make an offer or solicitation for the sale or purchase of any securities. Investing involves risk, including the potential loss of principal. No investment strategy, such as asset allocation or diversification, can guarantee a profit or protect against loss in periods of declining values. All investment strategies involve risk and have the potential for profit or loss. Changes in investment strategies, contributions or withdrawals, and economic conditions may materially affect the performance of your portfolio. There are no assurances that a portfolio will match or outperform any particular benchmark. Investors should carefully consider the investment objectives, risks, fees, and expenses before investing. Any financial services firms referenced in this material do not provide tax or legal advice. Please consult with your tax or legal professional regarding specific issues prior to making a tax or legal decision.
The performance information presented in the asset category section of this report is based on equal-weighted averages of the following Morningstar Categories: US Stocks (US Fund Large Blend, US Fund Mid-Cap Blend, US Fund Small-Blend), Foreign Stocks (US Fund Foreign Large Blend, US Fund Foreign Small/Mid Blend, US Fund Diversified Emerging Mkts), US Bonds (US Fund Intermediate Government, US Fund Inflation-Protected Bond, US Fund Corporate Bond, US Fund High Yield Bond, US Fund Bank Loan), Foreign Bonds (US Fund World Bond, US Fund Emerging Markets Bond), Hard Assets (US Fund Commodities Precious Metals, US Fund Commodities Energy, US Fund Global Real Estate, US Fund Real Estate), Hybrid Assets (US Fund Convertibles, US Fund Preferred Stock).
© 2026 Morningstar. All Rights Reserved. The information contained herein: (1) is proprietary to Morningstar and/or its content providers; (2) may not be copied or distributed; and (3) is not warranted to be accurate, complete, or timely. Neither Morningstar nor its content providers is responsible for any damages or losses arising from any use of this information. Past performance is no guarantee of future results. Morningstar category data is provided for illustrative purposes only to demonstrate a hypothetical investment vehicle represented by a group of similar investments. Morningstar category data is an aggregation across actual funds contained in the category, but it is not possible to directly invest in a category. Index returns are provided for illustrative purposes only to demonstrate a hypothetical investment vehicle using broad-based indices of securities. Unmanaged indexes are not available for direct investment. All data shown does not include internal fund expenses, trading costs, financial advisor fees, commissions, or taxes. This information is not intended to predict the performance of any specific investment or security. Past performance is no guarantee of future results.
Bureau of Labor Statistics. Unemployment Rate, Total Nonfarm Employment, Labor Force Participation, Consumer Price Index, Producers Price Index. www.bls.gov. United States, Department of Commerce, Bureau of Economic Analysis. Personal Consumption Expenditures, Gross Domestic Product, Consumer Spending, Personal Income, and Outlays. www.bea.gov. Federal Reserve. Fed Funds Rate, Fed Funds Target Range, Minutes of the Federal Open Market Committee, Board of the Federal Reserve System Calendar. www.federalreserve.gov. Trump, Donald. @realDonaldTrump. Truth Social.